From back office to competitive edge: what’s next for B2B payments in 2026
Beyond AI, the trends point to a broader transformation.
Executive summary
Payments have reached an inflection point. In 2025, businesses accelerated digitization, automation and global scaling. But in many cases, payments still remained a visible, manual step. Now, the shift is deeper. Payments are becoming embedded, intelligent and anticipatory, fundamentally reshaping how businesses buy, sell and manage cash.
B2B payments are disappearing in plain sight. By 2026, the most important innovations in commerce won’t be about faster checkout buttons or slicker portals, they’ll be about making payments so seamless that buyers hardly notice them at all.
This year’s predictions, informed by interviews with leaders from Lenovo, IDC, Mastercard and TreviPay, highlight the trends redefining B2B commerce: invisible payments, AI-driven finance, cross-border standardization, hyper-personalized terms, data-driven modernization and API-first integration. These are not incremental improvements; they are structural changes that will transform payments from a back-office necessity into a front-line competitive advantage.
The disappearance of payments as a separate, visible step
AI-driven credit risk and A/R automation
Simplified cross-border payments
Hyper-personalized and truly dynamic payment terms
Data-driven modernization – Augmented Finance Intelligence
ERP & API-first integration becomes standard
Prediction 1
The disappearance of payments as a separate, visible step
For decades, payments have been treated as the final hurdle, an isolated action that slows down processes, frustrates customers and drains resources. But that model is quickly becoming obsolete. By 2026, payments will cease to be a step at all. Instead, they will operate invisibly, woven directly into the systems and workflows businesses already use.

The most profound shift by 2026 will be the disappearance of payments as a separate, visible step. Imagine a purchase order that, once approved, automatically triggers an instant payment. Or a project milestone that effortlessly releases funds. This level of embeddedness is blurring the lines between operations and financial transactions. It’s a game-changer.
Key impacts
The numbers confirm the momentum: the invisible payments market is forecasted to grow at an 18.2% CAGR, surpassing $2.27 trillion by 2034. This transformation is powered by open APIs, ERP integration and customer demand for zero-touch, seamless experiences.
The implications are clear: companies that still see payments as a standalone back-office function will fall behind. Embedded finance will soon be an expectation, not a differentiator. Businesses that embrace invisible payments now will set the standard for efficiency and customer experience in the years ahead.
Reconciliation disappears as workflows and payments merge
Cash cycles accelerate, with funds released instantly upon triggers
Ease of buying becomes strategy, not simply convenience
Pay by Invoice
TreviPay’s Pay by Invoice shows what invisible payments look like in practice. Pay by Invoice embeds trade credit directly into the purchasing journey: buyers simply select “Pay by Invoice” at checkout, with no card details and no delays, while sellers offload credit, risk and settlement to TreviPay in the background. The result is a transaction that feels frictionless to the buyer and delivers confidence and efficiency to the seller.
Explore Pay by Invoice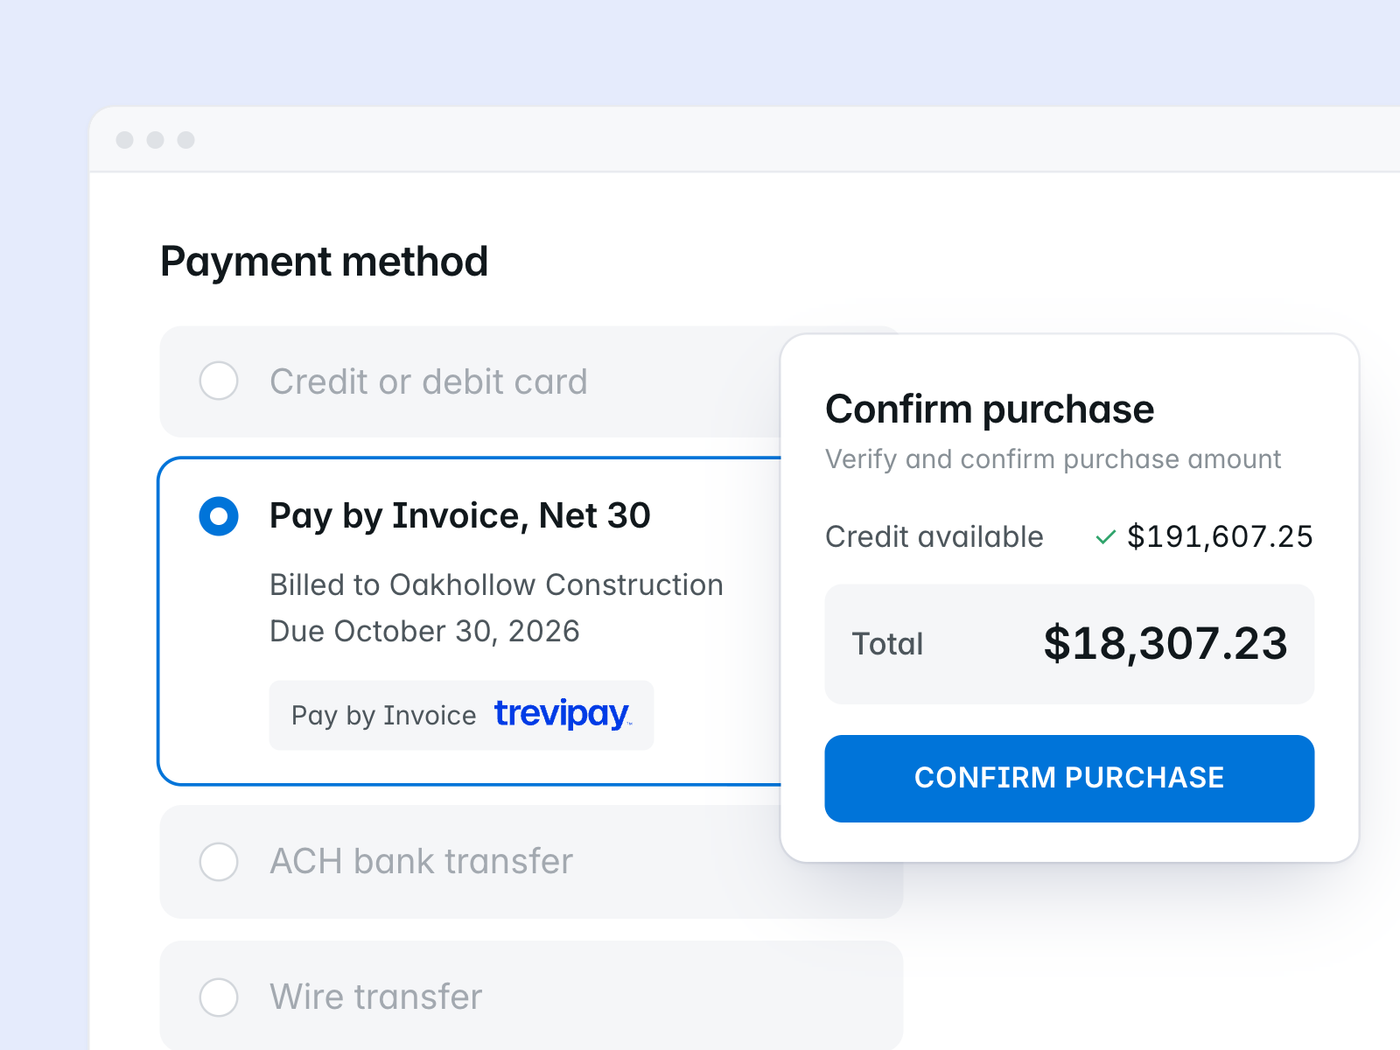
Prediction 2
AI-driven credit risk and A/R automation
Artificial intelligence has moved from buzzword to business driver. In finance, its impact will be transformative. By 2026, AI will be the engine that powers credit, invoicing and collections – not simply as automation, but as intelligence that anticipates risk, prevents revenue leakage and strengthens customer relationships.

Our use of technology must go beyond efficiency to deliver agility and real insights. We leverage AI to personalize experiences, power dynamic pricing and enable smarter decision making for our customers. Innovation isn’t optional, it’s a resilience multiplier.
What to expect
IDC’s Kevin Permenter expands: “AI won’t simply automate tasks; it will transform credit and collections into strategic profit centers. Collections will move from debt recovery to relationship preservation.”
“By 2026, 80% of finance leaders plan to increase AI investments in credit and collections. The result: finance teams will move from being cost centers to becoming revenue enablers, playing a central role in building agility, trust and resilience.” Source: CFO.com
Smarter credit
Real-time optimization of credit limits and terms.

Perfect invoicing
Intelligent automation of contractual billing nuances.

Proactive collections
AI will identify churn risks before they become defaults.

Zero Touch A/R
TreviPay’s Zero Touch A/R brings the vision of AI-powered finance to life by removing the burden of accounts receivable altogether. Combining AI, managed services and automation, it handles credit decisions, invoicing and collections while guaranteeing payment for sellers. Businesses gain cash flow certainty, buyers enjoy greater flexibility and A/R disappears as a manual function, freeing finance teams to focus on growth.
Explore A/R automation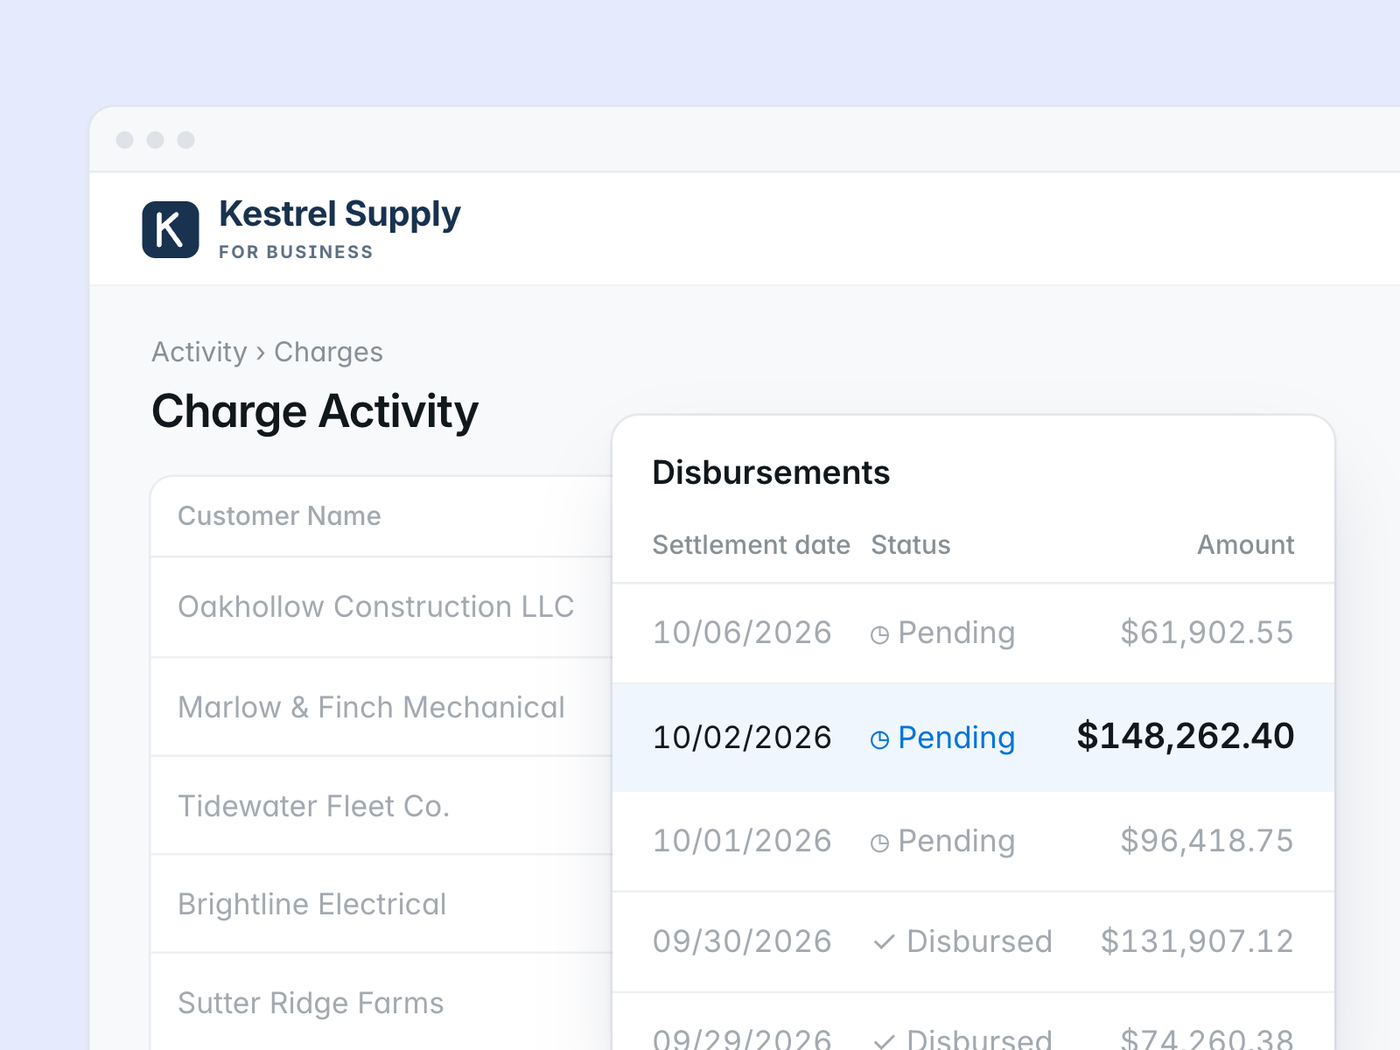
Prediction 3
Simplified cross-border payments
Global commerce is booming, but paying across borders sometimes can feel like navigating a maze. Fragmented platforms, compliance hurdles and FX complexity make cross-border transactions one of the biggest sources of friction in B2B.
Cross-border transactions bring regulatory hurdles, compliance complexity and customer expectations for omnichannel acceptance. Standardization is lacking, making reconciliation and reporting difficult. Businesses need integrated solutions that ease these challenges.
Key pain points
The winners will be those that make cross-border payments feel as simple as domestic ones. By investing in compliance-ready, multi-currency platforms, businesses can eliminate barriers to growth, reduce risk and unlock global opportunity.
Regulatory patchwork
KYC, AML and tax rules differ by region.
TreviPay supports local eInvoicing laws, tax formats and AML/KYC compliance, so you stay audit-ready across markets.

Platform fragmentation
No global standard for processing payments.
TreviPay builds in EN16931-compliant invoicing and Peppol connectivity.

Customer demand
Expectation of preferred methods, everywhere.
TreviPay runs net terms in 32 countries, with local currencies, languages and compliance.

Prediction 4
Hyper-personalized and truly dynamic payment terms
Rigid “Net 30” or “Net 60” terms are increasingly relics of the past. B2B buyers, empowered by technology and heightened expectations, want payment schedules that flex in real time with their cash flow, project cycles and market conditions.

Buyers will demand hyper-personalized, dynamic payment terms that adapt to their real-time financial health. Forget rigid terms: suppliers must proactively offer flexible, tailored options. The expectation won’t just be flexibility, but the perfect flexible option for me, right now.
Why it matters
Flexible terms turn negotiations into opportunities to build trust
Buyers will reward suppliers that anticipate and adapt to their needs
Innovation amid uncertainty
In 2026, payment flexibility will move from a differentiator to a baseline expectation. Economic uncertainty is speeding up the shift: suppliers need to protect their cash flow, and buyers expect flexible terms. Businesses that adopt real-time, adaptive terms will build deeper loyalty and stand out where competition is already at an all-time high.

Inflation, supply chain volatility and geopolitical disruption are driving businesses to seek faster, more reliable payment solutions. Net terms financing is evolving to provide greater predictability, offering buyers more control over Days Payable Outstanding (DPO) while giving suppliers confidence in Days Sales Outstanding (DSO).
Prediction 5
Data-driven modernization – Augmented Finance Intelligence
The next wave of finance modernization isn’t about automating more steps; it’s about unlocking intelligence from data. By 2026, finance teams will rely on “Augmented Finance Intelligence” to forecast economic shifts, optimize terms and strengthen customer engagement.
By 2026, tools for scenario planning, liquidity forecasting and a 360-degree customer financial view will be essential. These capabilities allow finance teams to engage customers from a place of deep understanding.
What it means
TreviPay’s Chief Product and Technology Officer Dan Zimmerman adds: “We’re flipping the narrative, using the vast amount of A/R data not just for efficiency, but to increase loyalty and drive sales. By 2026, we’ll see case studies of payments data directly driving revenue.”
With 75% of CFOs citing siloed data as a barrier to forecasting, the leaders of 2026 will be those that turn raw payment data into foresight, and foresight into growth.
Scenario planning
Model the impact of economic shifts in real time.

Customer 360
Unified financial profiles across payments, disputes and sales.

Compliance automation
Embedded tools reduce risk and reporting burdens.

Prediction 6
ERP & API-first integration becomes standard
The API-first era has arrived. By 2026, businesses won’t just expect platforms to “connect” – they’ll demand seamless integration across ERP, CRM and finance systems as the default way to operate.

Buyers will increasingly demand instant credit decisions, no-touch invoice integration and intelligent self-service support. Businesses will either build these capabilities, or partner with a fintech that already has.
 Dan ZimmermanChief Product and Technology Officer
The numbers underline the urgency
- Cross-border friction, per McKinsey
- 40%
- CFOs citing siloed data in forecasting
- 75%
- A/R leaders prioritizing ERP, per PYMNTS
- 85%
Benefits of API-first
Less reconciliation error through system-to-system syncing

Faster processing of credit and invoice workflows

One connected view of customer and cash positions

Expert roundtable: voices from the industry
The future of B2B payments isn’t being written by a single player; it’s being shaped by a chorus of experts across industries and regions.
Synthesis: Together, these perspectives show that the future won’t hinge on a single innovation, but on a convergence of trends—AI, embedded finance, compliance and integration—that elevate payments from a back-office function to a driver of resilience and growth.
Bob Cohen
“The saying ‘necessity is the mother of invention’ is more relevant than ever. In today’s complex economic and geopolitical landscape, inflation and supply chain volatility are driving businesses to seek faster, more reliable payment solutions. Uncertainty is spurring innovation, and those who adapt will turn change into a competitive edge.”
Director, Global Partnerships and Embedded Finance at Mastercard
Kevin Permenter
“Beyond automation, the essentials for finance teams by 2026 will be tools that foster ‘Augmented Finance Intelligence’—scenario planning, liquidity forecasting, and customer 360 views. These aren’t luxuries; they’re table stakes.”
Senior Director of Enterprise Applications Research at IDC
Piers Gorman
“It’s less about something shiny and new, and more about incremental steps that reduce friction, improve A/R and A/P efficiency, and ultimately lower cost. It’s about the 1 percent improvements that add up.”
TreviPay APAC
Dan Zimmerman
“What we’re seeing is the shift from payments as a process to payments as a platform. By 2026, every successful B2B company will treat payments as part of their value proposition.”
TreviPay
Inez Berkhof-Hollander
“Real-time settlement, structured e-invoicing and embedded finance will transform European B2B payments. But without modernizing IT and tightening compliance, companies won’t capture the benefits.”
TreviPay Europe
Now is the time to prepare
From invisible payments to AI-driven finance intelligence, 2026 is not just about efficiency, it’s about transformation. Companies that seize these trends will gain a head start in redefining customer experience, streamlining operations and unlocking new growth. Contact TreviPay to explore how our solutions can help embed intelligence, streamline global payments and lead the future of B2B commerce.